Categories
Home Buying TipsPublished October 9, 2026
Your Kid Got Into MIT. Should You Buy Near Campus Instead of Renting?
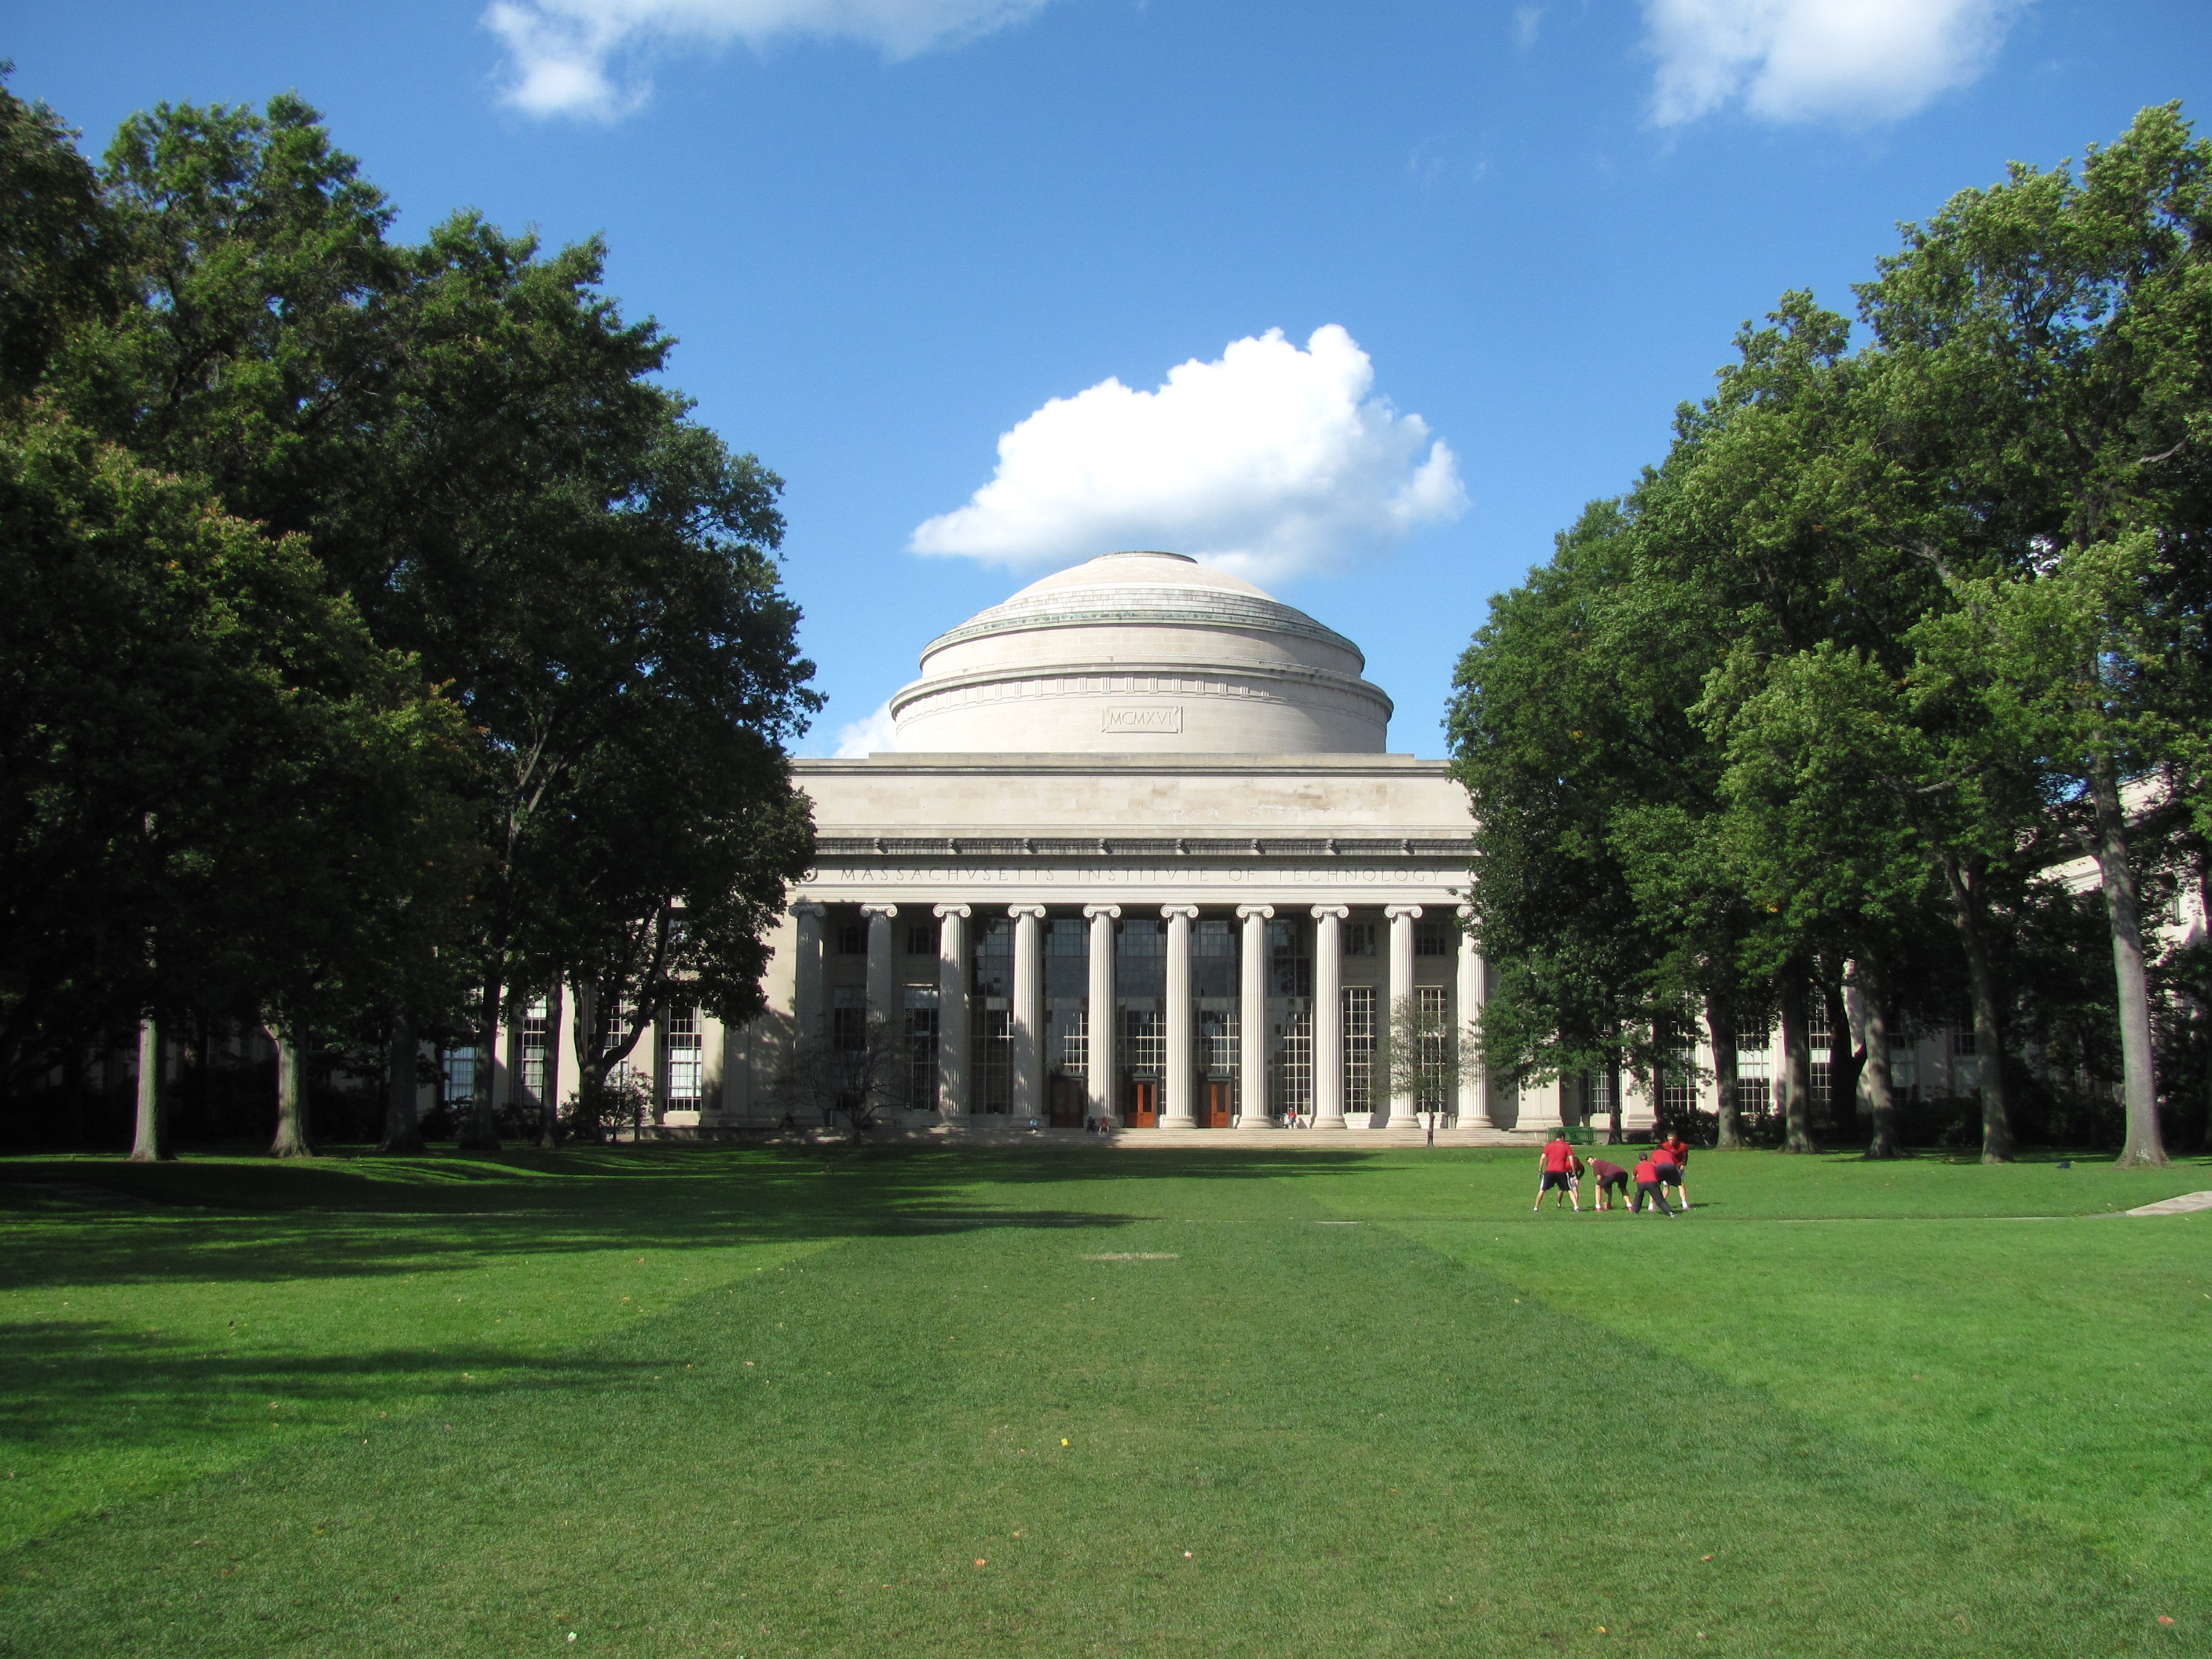
Once the MIT acceptance letter has been framed and the celebrating has settled down, many parents move on to a more practical question. You are already making a significant investment in your child's education. Would it also make sense to own a home a few minutes from campus, instead of paying for housing that leaves you with nothing at the end?
For a lot of the families we talk with, the question is not about finding the cheapest way through four years. It is about convenience, control, and putting capital into a market that has held its value well over time. Many are buying with cash, or could if they chose to. What they want is a clear-eyed view of whether a home near MIT (a condo, a single-family, or a small multi-family) is a sound place for that money, and how to set it up properly.
The answer depends on details that are very specific to MIT and Cambridge: MIT's housing rules, how Cambridge taxes owners who do not live in the home, whose name goes on the deed, and what you plan to do with the property after graduation.
Since 2014, the Santana Team has helped more than 1,600 clients buy, sell, and rent throughout Greater Boston, including in Cambridge and Somerville. Here is how we walk families through this decision.
The Short Version
- MIT requires first-year students to live on campus, so most families plan around sophomore year onward. That often means buying in the spring or summer after freshman year.
- Most families shop condos near campus, but a single-family or small multi-family can fit too. The strongest case combines convenience for your student with a multi-year hold in a market with limited supply and historically resilient values.
- Many of these purchases are cash purchases. Roommate rent can be a nice extra, but the plan should not depend on it.
- Decide early whose name goes on the title. It affects taxes, financing, association rules (for a condo), and what happens when you sell.
- Bring your CPA and attorney in before you make an offer, not after closing.
How MIT Housing Shapes Your Timing
According to MIT Housing & Residential Services, all first-year students are required to live on campus, and exceptions are rare. After that, undergraduates are guaranteed on-campus housing for eight consecutive semesters (summers excluded), as long as they submit the Housing Intent form each year. Students can also move into MIT-affiliated fraternities, sororities, and independent living groups after their first year, or live off campus.
So the realistic window for your student to live in a home you buy is about three academic years, plus summers if they stay in Cambridge for research or an internship. MIT's guarantee does not cover summer terms, which is one reason a year-round home base appeals to many families.
For context, MIT's published 2026-27 cost of attendance budgets $14,090 for an academic year of on-campus housing. Buying near campus is not really competing with that number. It is a different decision: owning an asset your family controls, in a location that will still be in demand long after graduation.
If your student is heading to Harvard, Northeastern, BU, or another Boston-area school, the same thinking applies, but residency rules differ by school. Review MIT's housing eligibility and first-year residency requirement and its off-campus housing resources.
Why Families Buy Near MIT
Convenience and control
A home near campus means no annual housing lottery, no hunting for a summer sublet, and no landlord deciding whether the lease renews. Your student has a quiet place to study, room for a desk that is not also a bed, and a home base that stays put through internships, research terms, and senior year. You have a comfortable place to stay when you visit, instead of booking Kendall Square hotel rooms on graduation weekend.
A multi-year hold, not a four-year expense
Families who buy with a longer horizon tend to be happiest with the decision. Many MIT graduates stay in Greater Boston for graduate school or a first job in Kendall Square, the Longwood medical area, or downtown. Others keep the condo as a rental. Either way, the purchase does not have to end when the diploma arrives.
A first lesson in ownership
There is also a quieter benefit. A young adult who lives in a home the family owns, pays attention to the condo association, notices when something needs repair, and understands what the monthly costs cover is learning how real estate works with the family behind them. For some families, this is the first step in their child building their own portfolio with parental support.
The Investment Case: Cambridge and Core Greater Boston
No one can promise appreciation, and we would not trust anyone who did. But the long-term record for Cambridge and the inner core of Greater Boston gives many buyers confidence, and current MLS activity still supports that view.
The Federal Housing Finance Agency's house price index for the Cambridge-Newton-Framingham metro division, which covers a much larger area than Cambridge itself, rose about 40% over the five years ending in the second quarter of 2026 and roughly 386% since 1991. You can see the figures in FHFA's HPI summary tables.
Closer to home, our analysis of MLS PIN data as of October 7, 2026 shows a busy Cambridge condo market. Through October 7, 413 Cambridge condos sold in 2026, at a median sale price of $952,500 (about $932 per square foot). That is a touch softer than the 2025 year-to-date median of $983,500, but sales pace stayed healthy: a median of 23 days on market and about 14 days to the first offer, with sale prices averaging 100% of list. Trailing twelve months, Cambridge recorded 533 condo sales. On October 7 there were 176 active condo listings citywide, or roughly four months of supply.
Across all property types (single-family, condo, and multi-family), Cambridge closed 745 sales in the twelve months ending October 7, 2026, at a median of $1,225,000, with sale prices averaging 101% of list. Much of that activity sits in the $500,000 to $2 million bands that matter for parent buyers, and homes priced between $1 million and $2 million often cleared at 102% to 104% of list.
Single-family and multi-family sales sit at a higher price point and still move quickly. Through October 7, 94 Cambridge single-family homes sold in 2026 at a median of $2,467,500 (about $971 per square foot), with a median of only 20 days on market and sale prices averaging 100% of list. Thirty-two were active on October 7 (about three months of supply). Multi-family sales were similarly firm: 62 sold year-to-date at a median of $2,150,000 (about $653 per square foot), a median of 29 days on market, sale prices averaging about 99% of list, and 27 active (about four months of supply). Those figures matter for context, and for families weighing a whole house or two-family near campus, but most parent buyers focused on a student home base still shop the condo inventory.
Supply is still constrained. Cambridge is a small, densely built city, and its Community Development Department has written about a slowdown in housing starts driven by construction and financing costs. Demand comes from MIT, Harvard, the hospitals, and the life science and technology employers clustered around Kendall Square. Kendall itself is a thin, condo-heavy micro-market: only four active condo listings on October 7, against about three months of supply.
The honest framing: Cambridge has historically shown strong demand, limited supply, and resilient values. Individual condos still perform differently based on the building, condition, layout, parking, and what you pay. Medians move year to year (Cambridge's 2026 condo median is slightly below 2025's so far), past performance is not a guarantee, and a three-year hold carries more timing risk than a ten-year one.
Where Families Look Near MIT
MIT's campus runs along Massachusetts Avenue and Memorial Drive between Central Square and Kendall Square. Most of the families we advise focus on Kendall Square, East Cambridge, Cambridgeport, and, across the river, Back Bay. Those pockets put your student within a walk, bike ride, or short T trip of campus without forcing a Kendall-only search. Figures below are condo-specific from our MLS PIN market reviews as of October 7, 2026 (2026 year-to-date through that date, unless noted).
Kendall Square
Kendall is closest to MIT's east campus and the Kendall/MIT Red Line station. Here you will find newer elevator buildings with concierge service, fitness rooms, and garage parking, alongside older stock. Full-service buildings are often the easiest choice for parents who live out of state, because building staff handle much of the day-to-day. It is also a thin pocket: only 14 Kendall Square condos sold in 2026 through October 7, at a median of $829,500 (about $938 per square foot), with a median of 34 days on market and sale prices averaging about 98% of list. Four were active on October 7 (roughly three months of supply). Kendall's for-sale inventory is mostly condos; single-family and multi-family sales there are rare, so the condo figures are the right ones for a student purchase. Expect fewer choices here than citywide Cambridge, and move quickly when the right unit appears.
East Cambridge
East Cambridge sits near the Lechmere Green Line station and a short hop from Kendall and MIT. Through October 7, 29 East Cambridge condos sold in 2026 at a median of $899,000 (about $916 per square foot), with a median of 37 days on market and sale prices averaging about 99% of list. Fifteen were active on October 7 (about five months of supply). Inventory is a bit deeper than Kendall, which gives families more room to compare buildings and layouts.
Cambridgeport
Cambridgeport sits between Central Square and the Charles River, just west of campus. It is mostly older two- and three-family houses, many converted into condos, some renovated to a high standard. Whole multi-families do trade here, but for a student home base the usual search is still the condo stock. Many addresses are a walk or short bike ride to MIT, and Magazine Beach Park on the river is close by. The condo market here has been competitive: 30 sales in 2026 through October 7 at a median of $1,291,500 (about $1,006 per square foot), with a median of only 14 days on market, about seven days to the first offer, and sale prices averaging about 107% of list. Ten were active on October 7 (about three months of supply). If you want Cambridgeport, be ready to compete.
Back Bay (across the river)
Some families prefer Back Bay, across the Harvard Bridge, if they want a Boston pied-à-terre their student can also use. Through October 7, 234 Back Bay condos sold in 2026 at a median of $1,400,000 (about $1,348 per square foot), with a median of 34 days on market and sale prices averaging about 98% of list. One hundred sixty-nine were active on October 7 (about seven months of supply), so the choice set is wider than in Kendall or Cambridgeport, at a higher price point.
Central Square and nearby
Central Square has its own Red Line station, restaurants and shops along Mass Ave, and the Route 1 bus past MIT. Some students do live there. For the families we usually advise on this purchase, though, Kendall, East Cambridge, Cambridgeport, and Back Bay are the more typical map. The Port (Area 4), north of Mass Ave between Central and Kendall, mixes older houses, small condo associations, and newer construction if you want something between Central and Kendall. A few families also look just over the Somerville line near Union Square or East Somerville on the Green Line Extension.
Many MIT students never need a car. The Red Line, the Route 1 bus, and Bluebikes cover most of daily life. If a deeded parking space matters to you, filter for it early. Older buildings often do not have one, and it can meaningfully affect resale value.
Paying Cash or Financing
A cash purchase is simpler and often more competitive. You can offer a faster closing with fewer contingencies, and you avoid lender rules about occupancy and condo project approval. Some buyers pay cash and then arrange financing afterward. If you are considering that, talk to a lender before closing so the paperwork is set up correctly.
If you finance, the loan type depends on who lives there. Under Fannie Mae's occupancy guidelines, parents buying for an adult child are generally not treated as owner-occupants. The exception applies to a physically handicapped or developmentally disabled adult child, not to college students. That usually leaves two paths:
- Second home: The borrower has to occupy it for part of the year, keep exclusive control, and it cannot be a rental property.
- Investment property: Usually a larger down payment and higher rate, but structured for rental income.
The building matters too. Lenders review condo associations, and a high share of rented units, pending litigation, or thin reserves can limit options. Freddie Mac's survey had the average 30-year fixed rate at 7.28% as of October 1, 2026, and second home and investment loans are often priced above that benchmark. Always describe occupancy honestly. It is a legal representation on the loan.
Whose Name Goes on the Title?
This is one of the most important decisions in the whole plan, and it is worth settling with your attorney and CPA before you make an offer. What follows is a general overview, not legal or tax advice.
Parents own it
This is the most common setup and keeps control with you. You decide when to sell, whether to rent, and how the property fits into your broader estate plan. The trade-off is that the property is generally not your principal residence, which affects the Cambridge residential exemption, loan classification, and how a sale is taxed.
Your student owns it, often funded by a gift
Some parents gift the purchase money and put the condo in their child's name, or name the student as a co-owner. For federal gift tax purposes, the 2026 annual exclusion is $19,000 per recipient, and each parent has their own exclusion. A gift large enough to buy a Cambridge condo will almost always exceed that, which generally means filing IRS Form 709. Filing a gift tax return does not usually mean paying gift tax. The amount above the annual exclusion counts against the donor's lifetime basic exclusion, which is $15,000,000 per person for 2026. See the IRS frequently asked questions on gift taxes.
How you make the gift matters. Gifting cash that your student then uses to buy the condo is different from buying it yourself and transferring it later. When property is gifted, the recipient generally takes over the donor's tax basis, as explained in IRS Publication 551, which affects capital gains when the property is eventually sold.
Putting the condo in your student's name has real advantages. If they live there as their main home, it may open the door to the Cambridge residential exemption and, later, the federal home sale exclusion, both covered below. It also means the property is legally theirs. That has implications for control, creditors, and future relationships, which is why some families use a trust instead. An attorney can explain the trade-offs.
Practical issues when your student is on the title
- Age: If your student is not yet 18 at purchase, ownership and signing need to be handled differently. Ask your attorney.
- Financing: A student with little credit history may not qualify alone. Some lenders allow parents as non-occupant co-borrowers or guarantors, which puts the parents on the hook for the debt. Programs and lender appetite vary.
- The condo association: The owner of record is a member of the association, receives the notices, votes at meetings, and is responsible for fees and assessments. Make sure your student is ready for that, or plan how the family will support them.
- Insurance and paperwork: The unit insurance policy, utilities, and tax bills should line up with how title is held.
Ask your closing attorney about the Massachusetts Declaration of Homestead too. It protects equity in a principal residence from certain creditors, and whether it applies depends on who owns the condo and who lives there. The Secretary of the Commonwealth's Homestead FAQ is a good starting point.
Tax Considerations for Buying Near MIT
This section is a high-level overview to help you have a better conversation with your CPA. It is not tax advice, and the right answer depends on your residency, income, ownership structure, and how the condo is used.
The Cambridge residential exemption
Cambridge's FY2026 residential tax rate is $6.67 per $1,000 of assessed value. Owners who occupy the property as their principal residence can receive a residential exemption of $510,208 off the assessed value, which reduced the FY2026 tax bill by about $3,403.
If you own the condo and do not live there, you should generally expect not to receive it. If your student owns the condo and lives there as their primary residence, they may be able to apply, but eligibility depends on their circumstances. Confirm with the Cambridge Assessing Department before counting on it. See the City's FY2026 property tax information.
Second home or investment property
The way the IRS treats the condo depends on its use, not just what you call it. If a family member lives there, the IRS generally counts those days as personal use unless that family member uses it as their main home and pays a fair rental price. That affects whether the condo is treated more like a second home or a rental, and what you can deduct. IRS Publication 527 and Topic 415 explain the personal-use rules.
If you finance, mortgage interest on a qualified second home may be deductible within IRS limits (see Publication 936). Property taxes fall under the federal SALT deduction cap, which is $40,400 for 2026 but phases down toward $10,000 for higher-income households. Many families buying at this level will find the property tax deduction offers limited federal benefit.
If roommates pay rent
When part of the condo is rented at a fair rate, that rental income is generally taxable, and a share of the expenses (condo fees, insurance, repairs, property taxes) may be deductible against it. The rented share of the building can generally be depreciated over 27.5 years. Depreciation lowers taxable rental income while you own the property, but it can be partly taxed back (recaptured) when you sell, so it is not free money. Expenses are usually split between rental and personal use.
When you sell
Gain on the sale of a condo you do not live in is generally taxed as a capital gain. The federal home sale exclusion of up to $250,000 ($500,000 for married couples filing jointly) applies only if the owner meets the ownership and use tests, which generally means owning the home and living in it as a main home for at least two of the five years before the sale. Periods when the home was not used as a main home can reduce the exclusion. See IRS Publication 523.
That is why the title question matters. A student who owns the condo and truly lives there for two years or more may qualify for the exclusion on their own sale. Parents who own it and live elsewhere generally will not.
Massachusetts-specific points
- Massachusetts taxes long-term capital gains at 5%. A 4% surtax applies to total taxable income above $1,107,750 for tax year 2026, and real estate gains count toward that threshold.
- Out-of-state owners generally still file a Massachusetts nonresident return to report the sale of Massachusetts property.
- Sellers pay the Massachusetts deed excise, which is $2.28 per $500 of the sale price, plus any county surcharge. Your closing attorney will confirm the exact amount.
See the Department of Revenue's Massachusetts tax rates and 4% surtax pages.
Smart Due Diligence on the Building
For a buyer who can comfortably carry the costs, the goal is not to minimize them. It is to understand what you are paying for and to protect the value of the asset.
- Condo fees: A three-unit association in a converted Cambridgeport house may have a modest fee covering master insurance, common utilities, and reserves. A full-service Kendall building costs more and includes staff and amenities. Ask what the fee covers and whether it is enough.
- Reserves and special assessments: Many small Cambridge associations are run by the owners themselves. Review the budget, reserve balance, recent minutes, and any planned roof, porch, masonry, or mechanical work.
- Leasing rules: Check the master deed and bylaws for leasing restrictions, minimum lease terms, or rental caps, especially if you might rent the unit after graduation.
- Insurance: Make sure your unit policy fits how the condo is used and owned.
- Resale features: Parking, outdoor space, in-unit laundry, layout, and building condition all influence how easily the condo will sell or rent later.
Roommates: Optional Upside, Not the Plan
Many families who buy in cash never take a dollar of roommate rent. Others like their student having a friend or two in the spare bedrooms, and some charge rent. If anyone pays rent, the owner is a landlord under Massachusetts law, even when the tenants are friends.
That means confirming the condo documents allow it, using written leases, and following Massachusetts security deposit rules, including holding deposits in a separate interest-bearing account at a Massachusetts bank. See the Commonwealth's guide to holding a security deposit. Federal and Massachusetts fair housing laws also apply when choosing tenants, and Massachusetts protections are broader than federal ones, so talk with your attorney about your setup.
Plan the Exit Before You Buy
Keep it as a long-term investment
Cambridge has a deep rental market tied to its universities, hospitals, and employers. Families who plan to hold for the long term often hire a property manager after graduation and treat the condo as part of their portfolio.
Your student stays
If your graduate takes a job or starts a PhD nearby, the condo can simply become their home. Depending on how title is held, that may involve a transfer or buyout, which your CPA and attorney should structure.
Sell after graduation
Selling after three or four years can work well, especially in a steady market. The outcome depends on your purchase price, market timing, selling costs, and how the gain is taxed under your ownership structure.
When Renting May Still Be the Better Fit
Buying is not right for every family. Staying on campus or renting may make more sense if your student is still deciding between dorms, an FSILG, or study abroad, if you do not want to manage a property from afar (even with help), or if your timeline is short enough that you would rather keep the capital elsewhere. Since August 1, 2025, Massachusetts landlords can no longer require tenants to pay the landlord's broker fee, which has made renting simpler for students. See the Commonwealth's broker fee FAQ.
Questions to Answer Before You Make an Offer
- Which years will our student actually live there, given MIT's first-year requirement?
- Whose name goes on the title, and have our CPA and attorney reviewed the gift, tax, and estate implications?
- Cash or financing? If we finance, is it a second home or an investment property?
- Do the condo documents allow leasing, and are there rental caps or minimum lease terms?
- How healthy are the reserves, and is any major work planned?
- Does the unit have the features that support resale, such as parking, outdoor space, and in-unit laundry?
- What is our plan after graduation: hold, hand it off, or sell?
How We Help Families Buying Near MIT
When parents come to us with this question, we start with their goals, not listings. From there, we narrow buildings near campus, compare fees and reserves, review recent sales and rental demand, and connect you with lenders, attorneys, CPAs, and property managers who know Cambridge condos.
We are a full team, so you have support from the first conversation through the search, the condo document review, the offer, inspections, and closing. That matters even more when you are buying from out of state or around a busy academic calendar.
We will be covering related topics soon, including condo buying for college-age buyers and roommate setups. In the meantime, our Greater Boston home buying guide explains how we help buyers prepare, evaluate properties, and get to closing.
Considering a Home Near MIT?
Whether you are ready to tour buildings in Kendall Square or Cambridgeport, or still deciding whether owning fits your family's plans, we are happy to talk it through. No pressure and no obligation, just a thoughtful conversation about what makes sense for you and your student.
Market figures for Cambridge (condo, single-family, multi-family, and all property types), Kendall Square, Cambridgeport, East Cambridge, and Back Bay are from Santana Team analysis of MLS PIN data as of October 7, 2026 (year-to-date and trailing twelve months as noted). Neighborhood condo figures are the focus near campus; citywide single-family and multi-family medians are included for context. Markets move. Price indexes, mortgage rates, property tax rates and exemptions, MIT housing policies, lending guidelines, and federal and Massachusetts tax rules can change over time. This article is not legal, tax, or mortgage advice. Confirm current details with MIT, the City of Cambridge, your lender, your attorney, and your CPA before making a decision.
Santana Team
| Santana Team | Keller Williams Boston Northwest
or another way